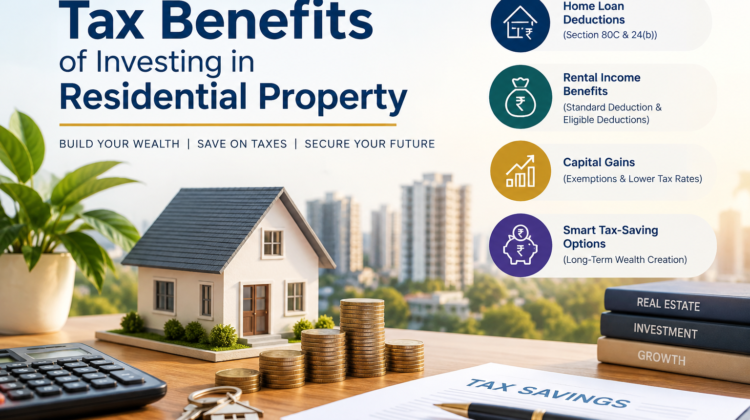
Tax Benefits of Investing in Residential Property
Housing property investment is often seen as a way to build long-term wealth through appreciation and rental income.
But, there might be another benefit to making residential property investments and it is your tax liabilities that are at stake!
If you are a property investor or are looking to buy a house, understanding the intricacies of property investment tax benefits could help you keep your taxable income in check and save you a pretty penny before year-end.
the Income-tax provisions do vary for self-occupancy versus rented property, home-loan financing, and other conditions.
Read ahead to find out more about the property investment tax benefits
Why Invest In Residential Property?
Any potential return on investment requires you to analyse the possible appreciation of value (e.g., you buy a flat in an area slated for expansion) as well as annual yield (rent).
Tax benefits can also significantly add to the financial benefit equation.
It goes without saying that all these factors need to be analysed to identify a profitable investment option. It is essential that you take into consideration the price of the housing property, rent, home loan interest rate, other expenses, and potential appreciation.
Let’s look at property investment tax benefits in more detail
1. Section 80C Of The Income Tax Act For Property Investment
As a homeowner, your tax-saving option includes the deduction in taxable income on a housing loan principal repayment.
Under Section 80C of the Income Tax Act, you can claim a deduction in respect of certain investments and payments. Eligible housing loan principal repayments are included in this deduction, but subject to the overall cap and applicable provisions.Section 80C encompasses a wide range of deductions, so a housing loan does not always entitle you to an extra deduction.
If you buy a house on a housing loan, you will probably find that the deduction under section 80C is critical to your property investment tax benefits.
2. Deduction On Home Loan Interest Payment
Another key property investment tax benefit comes in the form of a deduction on a housing loan interest payment.
Under section 24(b) of the Income Tax Act, you can claim a deduction in respect of interest on borrowed capital. This applies in the case of acquisition, construction, renewal, repair, or reconstruction of any house property.
Eligible taxpayers may claim the deduction for interest on a housing loan for a self-occupied house.
That is why, when calculating your overall cost of purchase, you must always factor-in a potential deduction on home loan interest payment: in particular, if a significant chunk of your monthly EMI instalments is made up of interest.
3. Rent Deduction For Property Investors
f you have decided to go the rental route as a property investor, you need to learn about rentals tax benefits!
You will be liable to pay taxes on the money earned from renting the house, which will fall under Income From House Property category. However, your renters tax deductions will depend on several factors, including a standard deduction and the deduction in respect of interest on borrowed capital.
A standard deduction is a percentage of net annual value that can be claimed as a renters tax deduction. Additionally, a section 24(b) deduction might be applicable, provided you satisfy all the conditions stipulated in this section. This means that your rental income tax may not be as high as you fear.
4. Understanding The Standard Deduction For Property Rentals
Your primary tax benefit as a property investor who rents out their property is the standard deduction.
Under the applicable provisions, you can claim a deduction in respect of standard deductions equal to thirty percent of the property’s net annual value.
It is useful in the sense that it is taken as an overall deduction and you do not have to itemize each expense that went into the maintenance of the property.
Note, though, that it is always good to understand the applicability and the provisions of the standard deduction to ensure that you do not overpay.
5. Capital Gains Tax On Property Sales
Another important area that needs to be considered while buying a house for investment purpose is capital gains tax on property sales.
When you sell an asset (in this case, a housing property) for a profit, you pay capital gains tax on the profit made on the sale. In the context of housing property, it entails determining the profit made on the sale of the house, computing appropriate tax under applicable conditions, and so on.
It always makes sense to find out which category your gain falls under (short-term or long-term) to estimate how much tax you will have to pay.
Note that tax laws are subject to amendment and therefore any capital gains tax should be calculated with reference to the relevant provisions for the relevant assessment year.
6. Capital Gains Tax Exemption: Tax Benefits On Property Sales
Under certain conditions, you may be able to claim an exemption on the capital gains arising on the sale of a house.
Under section 54, when you sell your long-term residential house, you can reinvest the proceeds in another residential house within the stipulated time and conditions for exemption under section 54.
Apart from section 54, there are many more exemptions on the tax due on the capital gains – once again, a property investor will have to evaluate each on its own merits.
So when you are thinking of selling, be sure to calculate the capital gains tax liability and examine the exemptions.
7. Joint Home Loan Tax Benefits For Married Couples
If you are contemplating a home-buying option with your spouse, you may want to look into joint home loan tax benefits.
If you buy a property jointly and both of you take a housing loan and are actually repaying it, both of you can claim a deduction under sections 80C and 24(b), subject to the limits.
This can be a really big deal as married couples buying residential property together may benefit from additional tax deductions.
Note, however, that merely putting your names on a loan does not make you entitled to a home loan tax deduction: there are several considerations that need to be taken into account if a couple is thinking of buying residential property on a joint home loan.
8. Old Vs New Tax Regime: Which One Is Better For You?
One of the most crucial considerations when contemplating residential property investment is understanding the applicable tax regime.
Several tax benefits of the old tax regime are not available under the new tax regime but again, it depends on what type of property you buy and how you use it. So do not assume that all benefits are applicable: make sure you compare and contrast and verify the relevant provisions before you decide to buy a house.
An appreciating property may require huge deductions to make it worthwhile. It is vital to keep these points in mind before deciding which property to buy.
FAQs: Tax Benefits of Investing in Residential Property
1. What are the main tax benefits of investing in residential property?
The main tax benefits can include eligible deductions on home-loan principal repayment, home-loan interest, standard deduction on rental income, and certain capital-gains exemptions, subject to applicable conditions.
2.Is rental income from residential property taxable?
Yes. Rental income from residential property is generally taxable under the head Income from House Property, after applying eligible deductions under the applicable tax rules.
3.Can I get tax benefits when selling a residential property?
Potentially. The sale of a residential property can result in capital gains, and certain exemptions may be available if the relevant statutory conditions are satisfied.
4.What is the tax benefit under Section 80C for home loans?
Eligible home-loan principal repayment can qualify for a deduction under Section 80C, subject to the overall Section 80C limit and applicable conditions.
5.How can I maximize tax benefits from residential property investment?

Pingback: Rental Property Investment: Is It Worth It in 2026?