Why Should You Care About Home Loan Interest Calculation? A Homebuyer’s Guide
Buying a home doesn’t happen everyday, and the home purchase is often an expensive affair. A loan secures you this big-ticket purchase, but how much will this loan really cost you? How much will you end up owing to the bank apart from the property you intend to buy. These are a few important questions you should be asking before going ahead with taking a home loan:
Understanding the various home loan calculations helps you gauge how a home loan will cost you and help you pick a loan tenure (tenure being the time over which you have to repay the loan) and compare one loan option to the other. This information, therefore, proves to be a handy guide when buying your dream home.
Understanding Your Home Loan Interest
The interest on your home loan represents the cost of raising a loan. You’ll have to make equal monthly payments i.e. an EMI (Equated Monthly Installment), which will include two parts:
The principal is what you borrow, while interest makes up the cost of borrowing. The weight of your EMI, during the first few years of your loan tenure will be more inclined towards the interest.
But as you go further into your plan, EMI repayment will be cut down into a mixture of both the money you’ve borrowed as well as the interest. To give you an actual idea, let’s say you had taken an interest-only home loan. During the repayment of such a loan, you would pay only the interest charges for several years. This could potentially reduce your monthly costs.
How’s a Home Loan Interest Computed?
The usual formula for computing the EMI owed on a home loan is:
E = P R (1 + R)^N / ((1 + R)^N – 1)
where
P stands for principal, or the loan amount taken
• R stands for rate of interest (per month, if it’s a monthly instalment)
• N is the number of instalments (monthly, if it’s a monthly instalment)
Say, for example, you took a ₹40 lakh home loan at a rate of 8.5% annual interest to be paid back over a period of 20 years. So, R, the monthly interest rate will be 8.5% divided by 12 = 0.7083%.
We can then apply the formula to find out our EMI payment. Your approximate EMI would come out to be around ₹34,700. But that would mean that overall, you will end up owing more than ₹40 lakh to the bank. In fact, if you add up the total amount of money you would be paying via EMI to the bank for the entire 20 years of your loan, it would be almost double your initial loan amount!
Actual EMI and overall interest will depend on the bank or lender’s calculation process
Let’s Try A Few Examples of Interest Calculation
Loan Amount Approx. EMI (20 Years) Approx. Total Interest
₹30 lakh ₹26,035 ₹32.48 lakh
₹40 lakh ₹34,713 ₹43.31 lakh
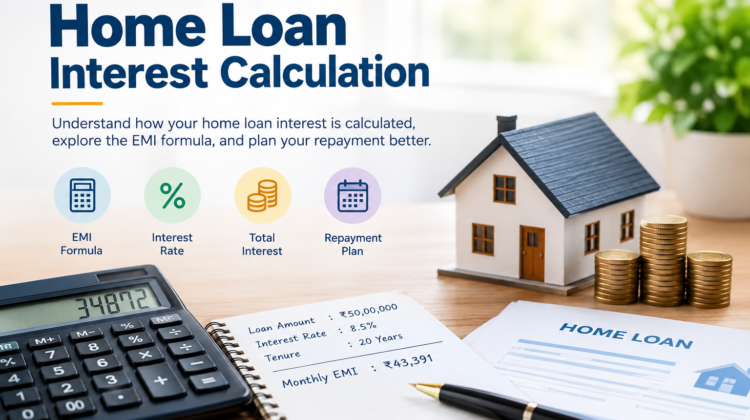
₹50 lakh ₹43,391 ₹54.14 lakh
This table is only a rough calculation and is based on approximated numbers. Try calculating a few values for yourself to gain a perspective on how EMI and interest are calculated. The interest amount fluctuates with a slight change in the interest rate and also with the kind of terms and conditions each lender sets to their borrower(s).
Note: These example calculations are done using the standard formula given earlier but may vary with the actual calculation made by a lender/banking institution.
Some Factors That Influence Interest
What factors determine the EMI due on a home loan? The interest amount due depends essentially on:
The actual loan amount: The higher the loan amount, the more interest it would attract
The loan tenure: The longer the duration for repayment, the lesser your EMIs would stand to be
Repayment: Making part-prepayments on your loan brings down the principal amount and subsequently, the interest paid on it.
The Bottom Line
Understanding the interest calculation is important when you’re thinking of taking a home loan. While the EMI amount on a loan could help you understand your monthly costs, it is the overall interest amount that adds right up to the total extra amount you end up owing to the bank for your mortgage. Try calculating several examples using an EMI calculator and understand the impact of every little change in your home loan amount, rate or the loan tenure before you plan to buy your dream home.
A home mortgage is a financial commitment, and it has to fit rightly within the larger context of your financial planning. By keeping track of how much you’d have to pay on your interest-only mortgage at any given point in time, you’ll be sure of the amount to be committed, every month, to your loan repayment. An EMI and interest calculator can make your task of calculating these amounts a lot easier, by simply substituting these values with whatever you input in a matter of seconds.